Two cold storage buildings can look about the same from the parking lot and price very differently. Same dock doors, same insulated panels. One is a modern freezer leased for a long term to a national operator, and the tenant pays the electric bill. The other is an older cooler, still occupied by the owner, and the owner pays the electric bill. That bill is not a small item. Refrigeration runs all day, and it is one of the largest expenses in the building. Who pays it changes the income a buyer is capitalizing, and it changes the risk if electricity prices move.
That difference lands in the value and in the cap rate. The leased freezer has a contract rent, a tenant paying the utilities, and a buyer who can underwrite the lease. It will usually support a lower cap rate. The owner-occupied freezer has no contract rent, an owner carrying the utilities, and time to find the next user. Each of these items produces a higher risk, and that risk will affect the cap rate.
Vacancy
The national vacancy number will not sort those two buildings out. Newmark Research put first-half 2026 vacancy at 7.7 percent, after the first negative first half of net absorption since 2007. The vintage split is the part that belongs in the market analysis.
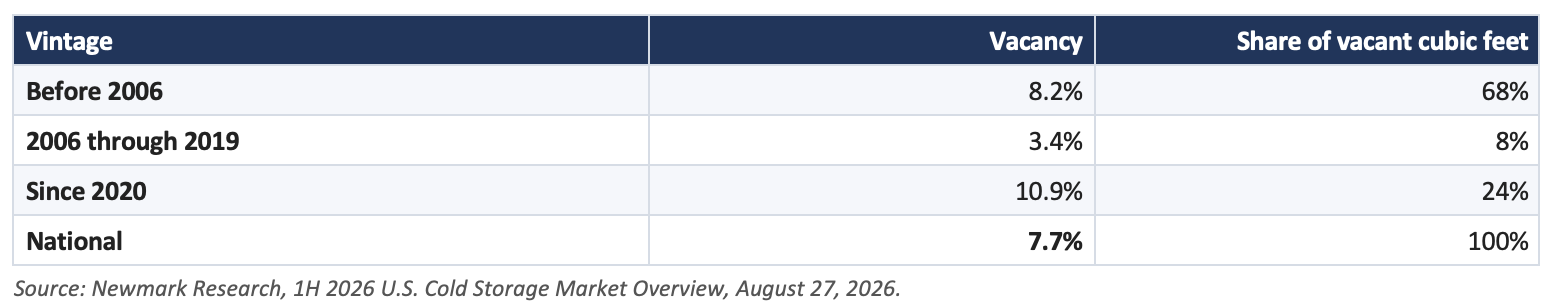
The pre-2006 stock holds most of the empty cubic feet. The 2006-to-2019 stock is the tight cohort. The post-2020 vacancy is mostly lease-up, and that product has taken nearly all of the recent demand. Vacancy is its own piece of the analysis. It tells you how long a building is likely to sit, and it tells you what a buyer will pay for the chance of that wait. A single 7.7 percent vacancy rate does not do that for both of these hypothetical buildings. The older cooler is competing with the stock that already holds most of the empty space. The modern freezer is competing with product that is still leasing up. Those are different markets, and the price should show it. Size matters too. Newmark reports the average cold storage lease signed over the past five years at about 125,000 square feet, while projects under construction average about 300,000 square feet. A large new building may wait longer for the right tenant, and that wait belongs in the cash flow or in the price.
Rent
Newmark reports that average cold storage lease rates have risen more than 100% since 2020, to $27.40 per square foot, roughly double the $13.15 per square foot average lease rate reports for new U.S. industrial leases overall. That gap is real, but the cold storage average is weighted heavily toward new, modern product. An older plant will not achieve the lease rate a recent delivery commands, even in the same market. Within a single building, lease rates also vary by temperature: freezer space generally leases above cooler space, and dock, ambient, and office areas lease lower still, so a blended rate can hide a lot.
Owners and lenders should also look closely at who pays the utilities. Refrigeration makes utilities one of the largest operating costs, and a gross lease where the landlord carries that expense produces a very different net income than a net lease at the same face rate. Where the landlord pays the utilities, the lease rate is typically higher to cover the bill, so the face rate alone does not tell you much.
Finally, the contract lease rate is evidence, not the answer. Leases signed at the peak of the market, sale-leasebacks priced to support a purchase, and leases where the tenant owns the refrigeration equipment can all differ from what the building would lease for today, and the appraiser will typically test the contract rate against current market evidence.
Cap Rates
Clients often start with a published dry-industrial cap rate and expect the appraisal to land close to it. Sometimes it does. A lot of the time it does not. Dry and cold use the same list in determining the level of risk a property carries: location, building quality, lease term, and whether the tenant can pay. The difference is how each of these is weighted. In a dry warehouse the next tenant is usually another distributor. In cold storage the tenant is usually the company running the plant. If that tenant leaves, a second-generation cold storage building can take longer to re-lease, and the owner is paying the power, the insurance, and the taxes while it sits. That downtime is why the credit and the remaining term have more of an effect on the cap rate.
There are three common setups for leased cold storage, and they do not price the same. A long net lease to a national operator with investment-grade credit is generally the lowest cap rate of the three. The tenant pays the expenses, the term is long, and a buyer can underwrite the rent without running the building. A five-year lease to a regional operator generally takes a higher cap rate. The term is shorter, the credit is usually thinner, and at expiration the owner needs another company that can operate a cold plant. A sale-leaseback to a food processor is the third. The buyer is getting a lease to that processor, not a building with several likely users if this processor eventually vacates. What that does to the cap rate depends on the tenant’s credit and on how specialized the plant is. Strong credit and a building another operator could use could warrant a lower cap rate. Weak credit, or a plant only that processor can run and that has limited other use without significant capital, could warrant a higher cap rate.
An owner-occupied plant is a fourth case, and it has no lease. In this case we develop an estimate of market rent based on how comparable cold storage leases are written in the market area. One caveat is that any storage and handling revenue, the labor, and the customer list belong to the business. The market lease rate for the building itself is often well below what the operation brings in. Often racking, some refrigeration components, and the refrigerant itself are personal property, and a lease may include those items and the cost of installing them. If those get capitalized into the building, the real estate value may not be accurate.
RealtyRates.com is the published survey I would use as a baseline, and it does not have a cold storage line. The closest industrial category is climate controlled and manufacturing. Self-storage has its own climate-controlled line. That is mini-storage, not a food plant, and it does not belong in this comparison. The third-quarter 2026 survey, which reports second-quarter data, put surveyed overall rates as follows.
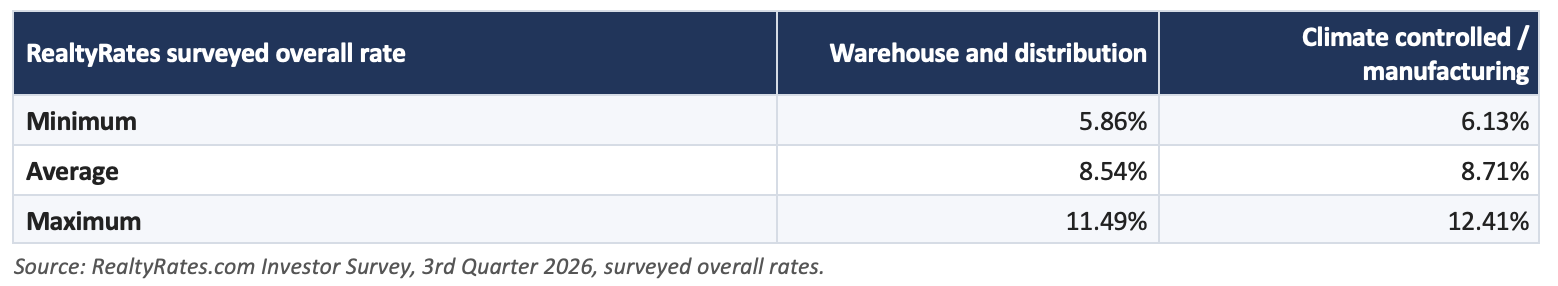
The averages are close, 8.54 percent for warehouse and distribution and 8.71 percent for climate controlled and manufacturing. The top of the climate-controlled range is wider. That is the useful part. A published average will not sort out the lease setups described above. If a dry-industrial survey is used at all, it is a baseline, not a conclusion. Modern cold storage on a long lease to a strong operator can price near good dry industrial. Older cold storage, and cold storage leased to a regional operator, usually prices wider for two reasons. The first is that fewer buyers can use the building. It takes the refrigeration plant, the power, and someone who knows how to run it. A typical industrial buyer will not take that on unless a tenant is already lined up. The second is a weak fallback, which can force a dry exit: stripping the cold storage out and leasing it as a regular warehouse. That conversion costs money, and a buyer will price it in.
The other public figures come from the operators, not from a survey of dry warehouses. Two of the largest are Americold and Lineage. Americold, on its first-quarter 2026 call, described contributing 12 U.S. facilities to a joint venture with EQT at about a 7 percent blended cap rate, with Americold keeping a 30 percent interest and continuing to operate the buildings. Lineage, in its August 2026 investor presentation, put reported private cold storage cap rates at 6 to 7 percent, against a higher rate implied by its own stock. Those figures are for large, modern portfolios with the operator still in the deal. They are not the cap rate for a regional lease or an owner-occupied plant. They do sit near the bottom of the RealtyRates climate-controlled range, which is where a national operator on a long lease should be.
Cost
The value surprise is usually the gap between cost and what a buyer will pay. Newmark Research’s construction figures are the ones I use to frame that gap.
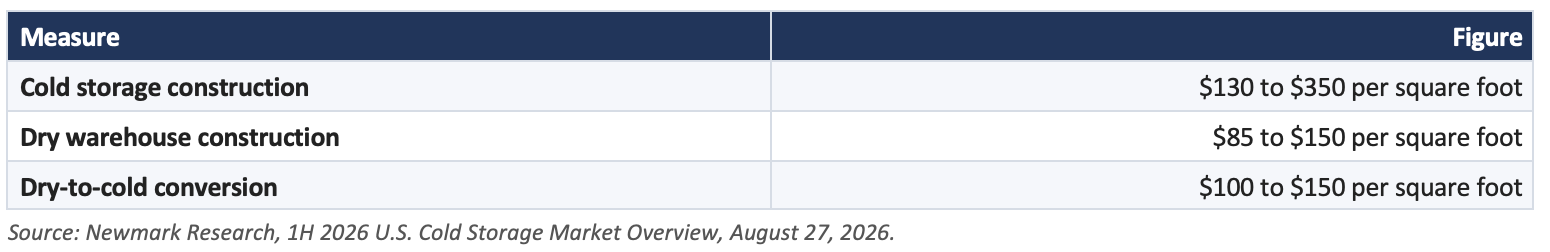
Cost is not the same thing as value. A buyer paying depreciated cost is assuming the rent supports it, the building leases in a normal period, and the capital in the plant is capital a buyer would keep. When those do not hold, the gap is obsolescence. It can show up as a higher cap rate or as a deduction for work a buyer has to do, not as an average of the cost and income approaches. Low clear height, a multistory layout, and a refrigerant being phased out are the usual reasons. A clean 1980s plant can still be the expensive one to own if the next user has to rebuild the refrigeration first. The panels, the blast cells, and the refrigeration are worth what the next user will pay. Another cold operator may pay for a share of that. A dry tenant generally will not.
Food processing assets are generally viewed as a different cost. Thomas Jensen, writing in Valuation in 2025, described a proposed seafood plant in Boston at over $800 a square foot before profit and land, and over $1,000 all in. At 6.5 percent that needed about $65 of net rent. Market rent there was about $32. The company was buying efficiency in its business and production process, not a real estate yield. The plant was built to raise earnings on the business side. The rent was never going to pay for that. In that market, developers often deliver the shell and leave the interior to the tenant, so the lease can look cheap against a building the tenant finished. Older plants often sold around $150 to $200 a square foot, with alterations that could exceed $200. The user who can move in without that work pays more. Money spent on a specialty plant does not come back, dollar for dollar, in the sale price.
Pharmaceutical and biologics cold chain is a further step out. Those tenants and buyers are paying for reliability, backup systems, temperature monitoring, and regulatory compliance, not just space. Certifications and validated systems belong in the risk analysis, and most food-grade buildings cannot serve that user without significant capital. A pharmaceutical exit should not be assumed for a food warehouse, and a facility built around one drug maker’s process may have a narrow set of next users.
The Use Sets the Rate
The two buildings in the opening show how no two cold storage properties are the same. One has a long lease, a tenant paying the utilities, and a buyer who can underwrite the rent. The other has no lease, an owner carrying the utilities, and time to find the next user. Credit, remaining term, and whether the next user can use the specialty cost are what move the cap rate. Vacancy and rent are their own evidence. Cost, including the cost of a processing plant built to raise earnings on the business side, may not transfer one for one into price. Like many other uses, cold storage gets filed under industrial. For a lot of purposes that is fine. For value, it is not enough. Knowing the use and its market is what leads to a market-supported cap rate.
For owners and lenders, the most useful thing to bring to an appraisal is complete information: leases and amendments, who pays the utilities and what they actually cost, the temperature breakdown by room, clear heights, pallet positions, the age and refrigerant of the refrigeration system, recent capital work, and any certifications. It also helps to confirm at engagement which interest is being appraised, the real estate alone or the real estate together with the operating business, since that changes what the appraisal measures. All of these things can have an impact on the rental rate, vacancy, cap rate and ultimately the value estimate. The better the information an appraiser has on the subject and comparable properties used for rents, sales and cap rates, the more supportable the value indication within the appraisal report.
Valbridge Property Advisors appraises cold storage and specialty industrial, including distribution, processing support, and underground facilities.
Sources: Newmark Research, 1H 2026 U.S. Cold Storage Market Overview, August 27, 2026. RealtyRates.com Investor Survey, 3rd Quarter 2026. Americold Realty Trust, Q1 2026 earnings call. Lineage, Inc., August 2026 investor presentation. Thomas J. Jensen, MAI, AI-GRS, “Cold-storage logistics,” Valuation, Issue 2, 2025.
The information contained in this publication is for informational and educational purposes only. It is not financial, legal, or other professional advice, and you may not rely on it for any purpose. To secure professional advice for your particular situation, you must engage one or more appropriate professional advisors to advise you about your situation.
Related Services
Comprehensive Valuation and Advisory Services